
Storm Damage Repair Under Your Deductible — Paid Direct, No Claim
Two cracked panes, a torn screen, a bent piece of fascia and a few chipped siding panels. Enough to fix, not enough to file. We quote it so you can see where it lands against your deductible and decide.
Storm damage repair under your deductible is work you pay for yourself because the damage costs less than the deductible on your policy, or close to it. JMB Builders does it across the Twin Cities metro the same way as a claim job: photos, a line-item scope, the repair, and a paid invoice you keep in case the storm turns out bigger than it looked. Priced per project. Whether to file is your call and your agent's.
- Priced per project, paid by check or direct deposit
- Same photos and line-item scope as a claim job
- Send photos, reply within one business day
- Free in-home estimate
- Licensed MN contractor BC809005
Send photos and hear back within one business day — or book a free in-home estimate.
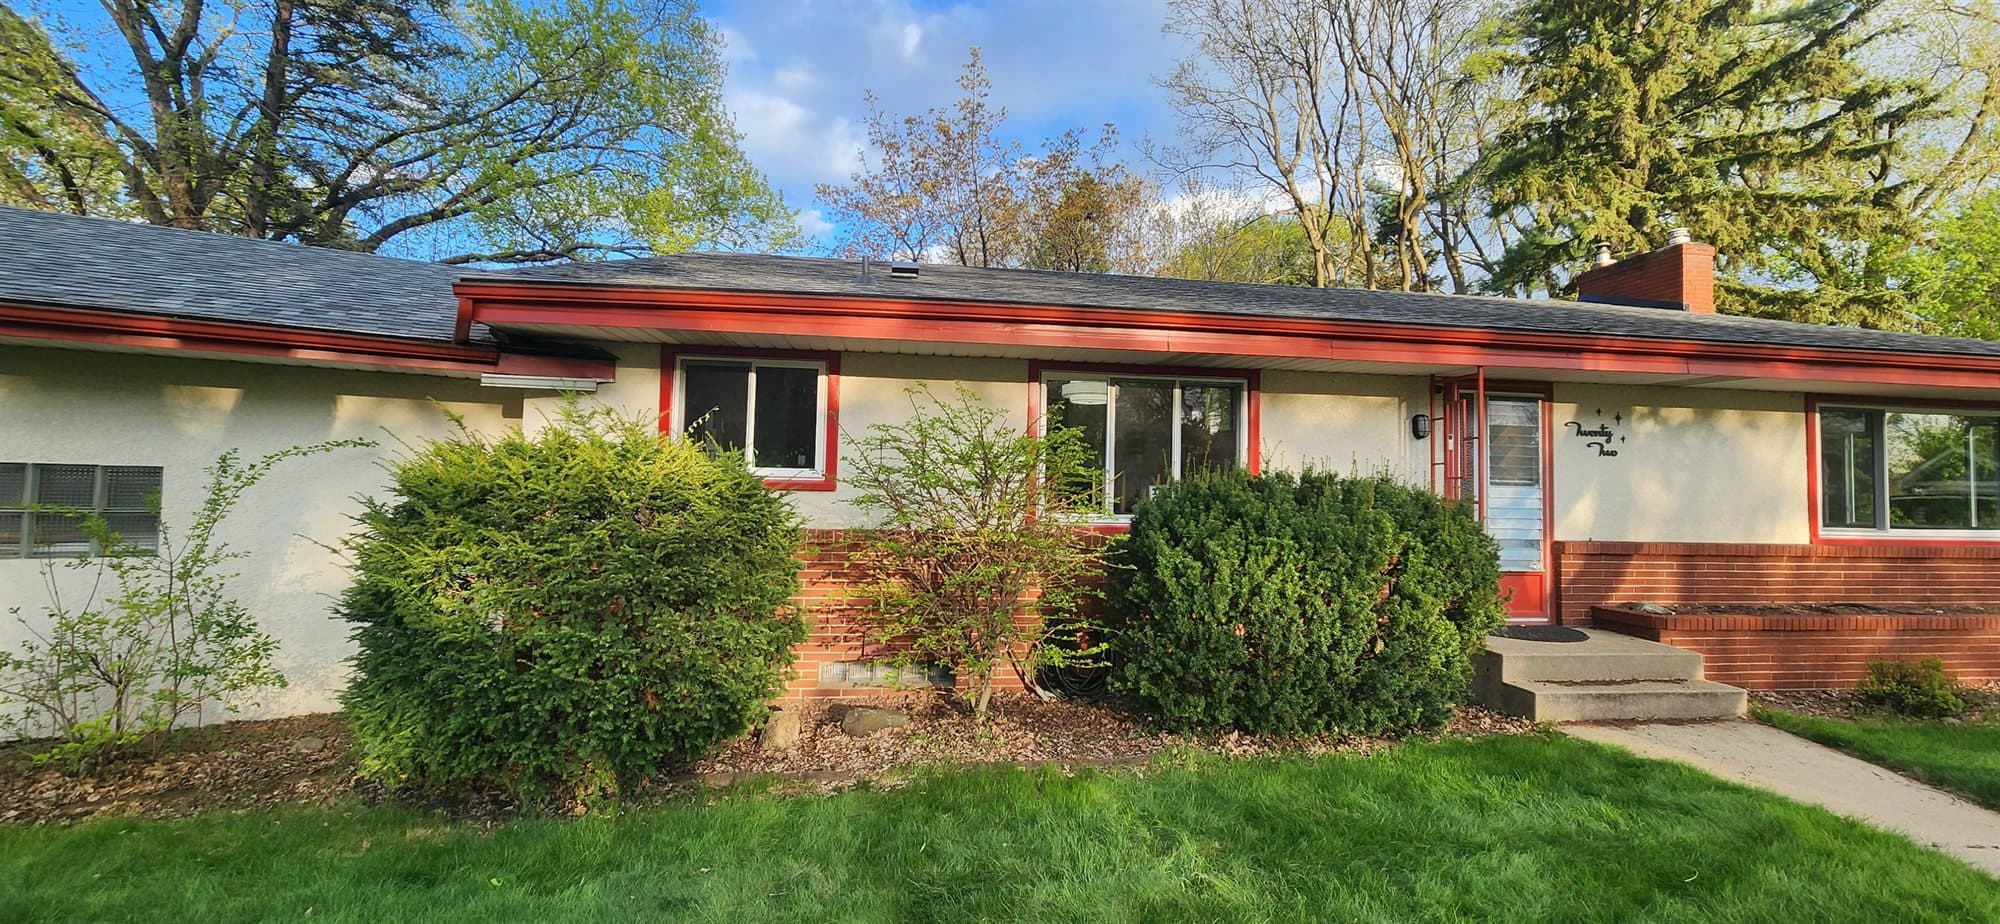
Not every storm is a claim. A policy with a percentage wind-and-hail deductible on a house in the north metro can have a deductible larger than the cost of replacing a few panes, a screen or a run of fascia. When the repair is under that number, filing gets you nothing and puts a claim on your record. When it is close, you need a real number before you decide. Either way the first step is the same: find everything the storm did, and price it.
We look at the whole house, not just what you noticed. Hail that cracked one pane usually dented the capping on the same side and tore the screens. Wind that bent one piece of fascia often lifted the shingle edge above it. We photograph each item and write the scope the way an adjuster would, one line per item, so you can compare the total to your deductible. If the total is under it, you pay us directly and the job is done. If it is over, you have the scope and photos ready to file.
We do not tell you whether to file. How a claim affects your premium, whether your policy counts a claim with no payout, and what your deductible is on wind and hail specifically are questions for your agent, and a quick call to them before you decide is worth it. What we do is give you a firm number and the documentation, so the decision is made with the facts in front of you.
What you supply
- Photos of the damage you have found, one wide shot per side of the house and a close shot of each item
- Your wind-and-hail deductible if you know it, so we can tell you how the total compares; or ask your agent
- Your choice of what to fix now and what to leave, once the scope is in your hands
- Payment by check or direct deposit when the work is done
What JMB supplies
- A walk around the whole house looking for storm damage you did not notice, with photos of every item
- A line-item scope in adjuster terms (unit, glass, screen, wrap, fascia, LF, SQ) with a price per line and a total
- The repair: glass, sashes, screens, siding panels, capping, fascia, trim, doors, whatever the storm hit
- Materials matched to what is on the house, or the closest current match with a note where it will show
- Painting of replaced wood trim when you want it done, quoted as its own line
- A paid invoice and the photos in your job folder, kept in case a later inspection finds more damage and you do file
- The same scope ready to submit if the total ends up over your deductible and you decide to file
How it is priced: per project
Quoted in writing from your photos, with a reply within one business day. What moves the number:
- How many items the storm hit once the whole house is checked, not just the first thing you saw
- Glass or sash replacement vs. a whole window unit
- Screens rescreened in the existing frames vs. new frames
- Siding and capping that can be matched from stock vs. a discontinued color
- Ladder work on a one-story house vs. staging on a second story
- Whether you fix everything on the scope or just the items that let water in
Send the photos and we reply within one business day with what else to look for. The firm number comes from the scope after we have seen the house, so you can set it next to your deductible before deciding anything.
How long it takes
A handful of items on one house: one day on site once materials are in. Glass and screens typically arrive within a couple of weeks of measuring; stock siding and trim sooner.
How your project works
- 1
Send photos, get a written quote
Send three photos of the space and a sentence about what you want. You get a clear, itemized reply within one business day. Prefer a look in person? A free in-home estimate is always an option.
- 2
Pick materials, or bring your own
We help you choose profiles and materials that fit the house and the budget, or match your existing millwork exactly — or you buy the door or trim yourself and we install it. Everything is confirmed before the crew is scheduled.
- 3
Clean, precise installation
The crew shows up on time, protects floors and furniture, and installs with tight joints and consistent reveals. Photos of the finished work go in your job folder.
- 4
Walkthrough and invoice
We walk the finished work with you. If anything is not right, we fix it before we call the job done. Then one invoice, paid by check or direct deposit — no card fees, no payment links.
Situations and options
Fix everything, pay direct
The scope total is under your deductible. We do every line, you pay by check or direct deposit, and the invoice and photos sit in your folder. Nothing goes to the insurer unless you choose to send it.
Fix what leaks, leave the cosmetic
You want the cracked glass and the torn fascia fixed now and are willing to live with dented capping. We price each line so you can drop the ones you do not want. The dropped items stay on the scope in case you file later.
Scope first, decide later
You are not sure the total is under the deductible. We write the scope and photograph the house, you take it to your agent, and the repair is scheduled once you know whether it is a claim or a direct job. The scope is the same document either way.
It grew into a claim
We found more than you saw: lifted shingles, cracked siding on two more walls. The total clears the deductible and you decide to file. The scope and photos we already wrote are what the adjuster gets. You file; we do the work once it is approved.
Storm Damage Repair Under Your Deductible — Paid Direct, No Claim: questions, answered
Should I file a claim for storm damage that is less than my deductible?
If the repair costs less than your deductible, the insurer pays nothing, so most people do not file. Whether a filed claim with no payout affects your premium or your record depends on your insurer, and that is a question for your agent. What we can do is give you a firm scope and total so you know which side of the deductible you are on before you call anyone.
How do I find out what my wind and hail deductible is?
It is on the declarations page of your policy, often as a separate line from the standard deductible and often as a percentage of the dwelling coverage rather than a flat amount. If you cannot find it, ask your agent; it takes them a minute. Knowing that number is the whole decision, so get it before you decide not to file.
Can a contractor just absorb the deductible so I can file anyway?
No. Minnesota law does not allow a residential contractor to waive, rebate, pay or promise to pay any part of your insurance deductible, and a contractor who offers to is breaking that law. If the repair is under your deductible, you pay for the repair. If it is over, you pay the deductible and the insurer pays the rest according to your policy. There is no third option.
What if more damage shows up after I pay for a small repair myself?
That is why we photograph the whole house and write the full scope even on a direct-pay job. If a roofer later finds hail on the roof, or a neighbor's claim gets you looking closer, the photos and the paid invoice from the first repair are part of the record. Whether the earlier repair can be added to a later claim depends on your policy and the dates, so ask your agent. You will have the paperwork either way.
Do you check the roof when you look at small hail damage?
We look at it from the ground and the ladder and tell you what we see at the edges, the vents and the ridge. Hail that cracked glass on one side of the house hit the roof slope above it too. A roof inspection is its own visit on the roofing side, and if what we see from the ladder says the roof needs a look, we tell you before you decide the storm was small.
Does a direct-pay storm repair cost the same as an insurance repair?
The work is the same and so is the price per line. What changes is the paperwork: on a direct job there is no adjuster scope to match, no supplement and no depreciation holdback, so you get one quote, one invoice and one payment by check or direct deposit when it is done.
Recent JMB work, from our job log
59 installs recorded across 30 Twin Cities communities since Dec 2025. Window and door installs for homeowners, builders and dealers. Counts come straight from our job log; no customer names.
Get a written quote for this job
Three photos and a sentence is enough: a reply within one business day, or ask for a free in-home estimate. Or text the photos to 763-204-2099.
Related jobs we do
Hail Damage Window Replacement — Cracked Glass, Sashes and Frames
Hail left star cracks in the glass, dents in the vinyl sill and a sash that will not close tight. Here is how each one gets fixed, and what goes on the list for your adjuster.
Read moreHail Damaged Window Screens Replacement — Rescreen or New Frames
Hail shredded the screens on the storm side and dented a few frames. Before anything gets fixed, every screen gets counted, sized and photographed so none is left off the claim.
Read moreSiding Repair — Storm, Hail and Woodpecker Damage
Wind took a run of siding off the gable, hail cracked the west wall, or a woodpecker found the LP — we repair the section, fix what is under it, and match it as close as the product allows.
Read moreStorm Chaser vs Local Contractor — How to Vet One in Minnesota
The morning after the hail there are trucks on every block and a card in your door. Some of them are good. Here is how to tell, without taking anyone's word for it, including ours.
Read moreActual Cash Value vs Replacement Cost — Why the First Check Is Less
The adjuster's estimate says one number, the check that came says a smaller one, and the letter mentions depreciation. Nothing is wrong. Here is what the numbers are and what has to happen for the rest to arrive.
Read moreAdjuster Says Hail Damage to Windows Is Cosmetic — What to Photograph
The adjuster walked around, saw dents and chips, and called it cosmetic. Before you accept that, check each window for damage that affects how it works.
Read morePage reviewed October 1, 2026 · JMB Builders LLC, MN license BC809005 · All insurance repairs pages
Where we work
Insurance repairs near you
Based in Zimmerman, scheduling across the Twin Cities metro. Closest first: