
Upgrading Windows on an Insurance Claim — Pay the Difference
The hail made the decision for you: the windows are coming out. If you were going to replace them in five years anyway, this is the time to get the ones you wanted, and here is how the money splits.
Upgrading windows on an insurance claim works like this: the approved scope pays to put back windows of like kind and quality, and anything better is a separate line you pay directly. Triple pane, a casement where a slider was, black frames, fiberglass instead of vinyl or a different brand are all upgrades. JMB Builders writes the claim lines and the upgrade lines apart so the adjuster sees one and you see both. Twin Cities metro, priced per window.
- Scope pays like kind and quality; you pay the difference
- Upgrade written as its own line, never hidden in the claim
- Depreciation on the approved lines still releases
- Send photos, reply within one business day
- Licensed MN contractor BC809005
Send photos and hear back within one business day — or book a free in-home estimate.
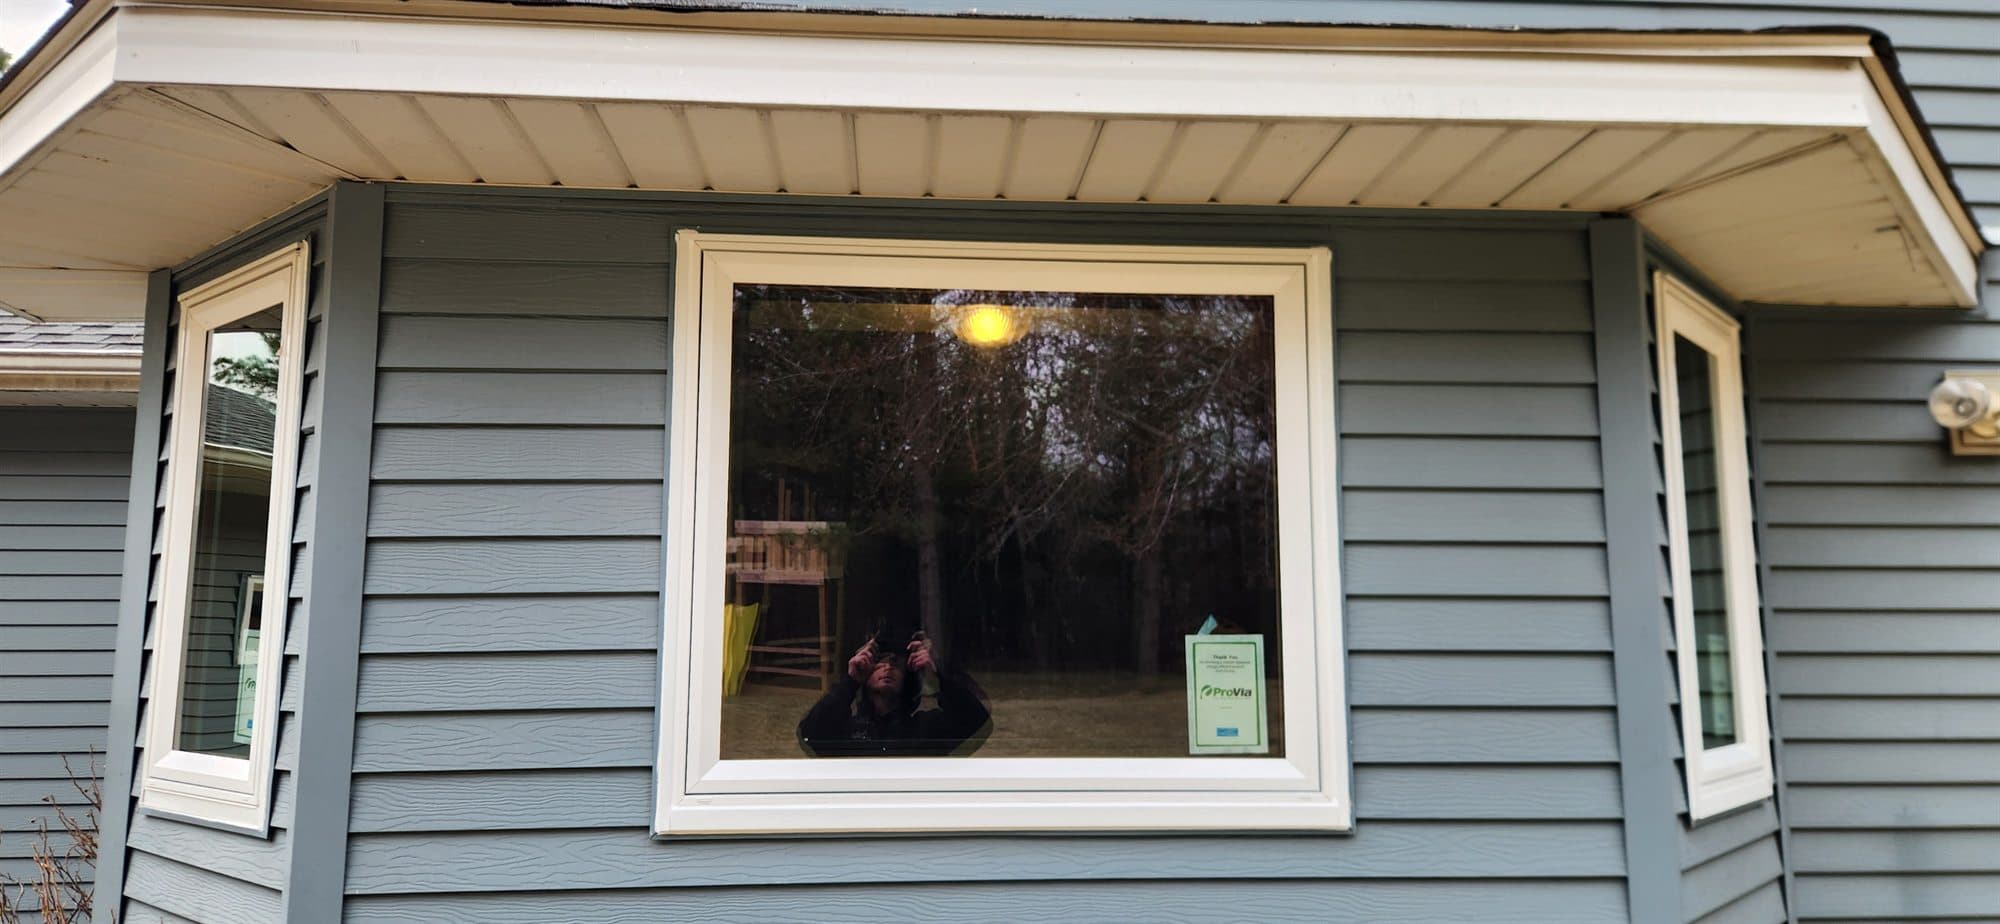
An insurance scope puts the house back the way it was. The adjuster prices each damaged window as a like-kind replacement: same type, same size, same frame material, same glass, near the same grade. That is what the policy owes. It does not owe you triple pane, a different style or the brand your neighbor has. But nothing stops you from buying those, and a claim that already has every window on the storm side coming out is the cheapest time you will ever have to do it, because the labor, the trim and the disruption are already paid for once.
The money splits cleanly when the paperwork does. Our quote has two kinds of lines. Claim lines match the approved scope item for item: window 6, double hung, vinyl, white, low-E double pane, with flashing and trim. Upgrade lines sit under them: window 6, upgrade to triple pane, or upgrade to casement, or upgrade to fiberglass. You pay the upgrade lines directly. The final invoice to your insurer shows the claim lines; the upgrade lines are between you and us. On a replacement-cost policy the depreciation on the claim lines still releases when the work is done, because the work on those lines was done.
A few upgrades are not upgrades. Tempered glass where code now requires it, egress size in a bedroom window, and current energy code glass can be required by the inspector when a window is replaced, and some policies carry ordinance or law coverage for them; ask your agent. And when the maker no longer sells the window you had, the nearest current product is like kind, not an upgrade. You file the claim and settle those questions with your insurer; we write the lines so each one is easy to see.
What you supply
- The adjuster's approved scope and the claim number
- Which windows you want upgraded and how: glass, style, color, frame material or brand
- A decision on the upgrades before the order goes in, since a window cannot be changed once it is built
- Your paint or stain color if interior trim changes with the new style — painting is quoted as a separate line, or paint it yourself
What JMB supplies
- Claim lines that match the approved scope item for item
- Upgrade lines under each window showing only the difference you pay
- Measurements and a check that an upgraded style fits the existing opening and the room's egress and tempered-glass rules
- Options such as the maker you had or others in triple pane, fiberglass, clad wood, casement or black frames
- Install of the upgraded units with sill pan, flashing tape, foam, sealant and interior trim reset
- A final invoice for your insurer that shows the claim lines, and a separate invoice to you for the upgrades
- Finished photos in your job folder
How it is priced: per window
Quoted in writing from your photos, with a reply within one business day. What moves the number:
- Glass upgrade: double to triple pane, different low-E coating, laminated or tempered where not required
- Style change: slider to casement, double hung to awning, two windows to one picture unit with flankers
- Frame material: vinyl to fiberglass or clad wood, which also changes the exterior trim detail
- Color: a dark exterior finish or a stained interior instead of white
- Brand change to a maker other than the one the adjuster priced
- Opening changes for a different size, which add framing, siding and drywall work the claim does not cover
Send the approved scope and tell us what you wish the windows were. We reply within one business day with which items are upgrades and which are like kind.
How long it takes
Upgrades do not slow the claim if they are decided before the order. Upgraded units can carry a longer lead time than stock; the install itself takes the same time as a like-kind replacement.
How your project works
- 1
Send photos, get a written quote
Send three photos of the space and a sentence about what you want. You get a clear, itemized reply within one business day. Prefer a look in person? A free in-home estimate is always an option.
- 2
Pick materials, or bring your own
We help you choose profiles and materials that fit the house and the budget, or match your existing millwork exactly — or you buy the door or trim yourself and we install it. Everything is confirmed before the crew is scheduled.
- 3
Clean, precise installation
The crew shows up on time, protects floors and furniture, and installs with tight joints and consistent reveals. Photos of the finished work go in your job folder.
- 4
Walkthrough and invoice
We walk the finished work with you. If anything is not right, we fix it before we call the job done. Then one invoice, paid by check or direct deposit — no card fees, no payment links.
Situations and options
Triple pane in the same window
Same style, same frame, heavier glass. The best cold-climate upgrade for the money because nothing else about the install changes. Heavier sashes may need a different balance or hinge, which the maker handles.
Casement where a slider or double hung was
Same rough opening, different operation. A casement seals tighter in wind and cranks clear for egress. The upgrade is the price difference between the two units; trim and flashing are already on the claim.
Fiberglass or clad wood instead of vinyl
A stiffer frame that takes a dark color and a narrower profile. The exterior trim detail changes with the frame, so the upgrade line may carry a little extra trim labor as well as the unit.
A different brand
The adjuster priced a like-kind unit, not a specific maker. You can choose any brand that fits the opening; the claim pays the like-kind amount and the difference, if any, is yours. Lead time follows the maker you pick.
A bigger or different-shaped opening
Two small windows into one picture window, or a taller unit in a bedroom. This is a remodel riding on a claim: the framing, header, siding and drywall are upgrade lines, and the window is like kind only up to the size you had.
Upgrading Windows on an Insurance Claim — Pay the Difference: questions, answered
Can I get better windows than I had on an insurance claim?
Yes. The claim pays to replace what you had with like kind and quality. Anything better is yours to buy as the difference between the two. We write the claim lines to match the approved scope and the upgrade lines separately, so the insurer sees what the policy owes and you see what the upgrade adds. Decide before the order goes in; a built window cannot be changed.
What does like kind and quality mean for windows?
The same type of window, in the same size, frame material, glass and near the same grade as the one that was damaged. A white vinyl double hung with low-E double pane is replaced with a white vinyl double hung with low-E double pane. When the exact product is discontinued, the nearest current product from the maker is like kind. Triple pane, a different style, a dark color or a different frame material are better than like kind, so they are upgrades.
If I upgrade to triple pane, do I still get my recoverable depreciation?
Generally yes, because the work on the approved lines was done; the insurer held back depreciation on a like-kind window and a like-kind window or better went in. The final invoice to your insurer shows the claim lines. The upgrade is on a separate invoice to you. How and when depreciation is released is between you and your insurer, so ask your adjuster when you send the invoice.
Can I switch to a different window brand than the one on the adjuster's estimate?
Yes. The adjuster's estimate prices a like-kind window; it does not require a brand. You can choose any maker whose unit fits the opening and meets code. If the unit you choose costs more than the like-kind amount, you pay the difference. If it costs the same or less, there is no upgrade line.
Can I change my window style, like casement instead of a slider, on a storm claim?
Yes, as long as the new style fits the existing opening and the room still meets egress and tempered-glass rules. The claim pays the like-kind amount for the slider; the difference to a casement is your upgrade line. A bedroom casement must still open to the code egress size, and we check that before anything is ordered.
Is tempered glass or egress size an upgrade or part of the claim?
Neither, exactly. They are code items the inspector may require when a window is replaced, not something you chose. Some policies include ordinance or law coverage that pays for code-required changes, and some do not; ask your agent what yours says. We list code items as their own lines so the adjuster can see them, separate from both the like-kind replacement and any upgrade you picked.
Recent JMB work, from our job log
59 installs recorded across 30 Twin Cities communities since Dec 2025. Window and door installs for homeowners, builders and dealers. Counts come straight from our job log; no customer names.
Get a written quote for this job
Three photos and a sentence is enough: a reply within one business day, or ask for a free in-home estimate. Or text the photos to 763-333-4066.
Related jobs we do
Insurance Claim Window Replacement — From the Storm to New Windows
Hail or straight-line wind took out windows on one side of the house and you have never filed a claim. Here is the whole path, from the first photos to the last check.
Read moreWindow Claim Code Upgrades — Egress, Tempered Glass, Energy Code
The hail broke a bedroom window from the 1970s. The replacement has to open big enough to climb out of, and the one next to the tub has to be tempered. Who pays for the code part is the question.
Read moreWhole-House Window Replacement on a Storm Claim — Every Side Hit
The hail came in sideways and then the wind turned, so every side of the house took hits. Twenty windows on one claim is a different job than two, and the scope has to be organized like one.
Read moreActual Cash Value vs Replacement Cost — Why the First Check Is Less
The adjuster's estimate says one number, the check that came says a smaller one, and the letter mentions depreciation. Nothing is wrong. Here is what the numbers are and what has to happen for the rest to arrive.
Read moreFiberglass Window Replacement — Stiff Frames, Dark Colors, Paintable
You want a black or dark exterior, a slimmer frame, or a window you can paint later. Fiberglass handles all three; we measure, order and install it.
Read moreAdjuster Says Hail Damage to Windows Is Cosmetic — What to Photograph
The adjuster walked around, saw dents and chips, and called it cosmetic. Before you accept that, check each window for damage that affects how it works.
Read morePage reviewed October 2, 2026 · JMB Builders LLC, MN license BC809005 · All insurance repairs pages
Where we work
Insurance repairs near you
Based in Zimmerman, scheduling across the Twin Cities metro. Closest first: