
Date of Loss for Hail Claim on Windows — Pinning the Storm
Two hailstorms came through this summer and you did not check the windows until fall.
Reply within one business day. Or call / text 763-204-2099.
The date of loss for hail claim purposes is the day the storm hit your house, and the claim is tied to it. Pinning it on windows and doors takes public storm reports for your address, dated photos, and signs that the damage is fresh: clean breaks, bright metal in dents, torn screens. JMB Builders documents those signs across the Twin Cities metro so you can give your insurer one date. Priced per window for the repair.
- Storm reports, dated photos and fresh-damage signs
- Fresh vs old damage noted window by window
- You file and choose the date with your insurer
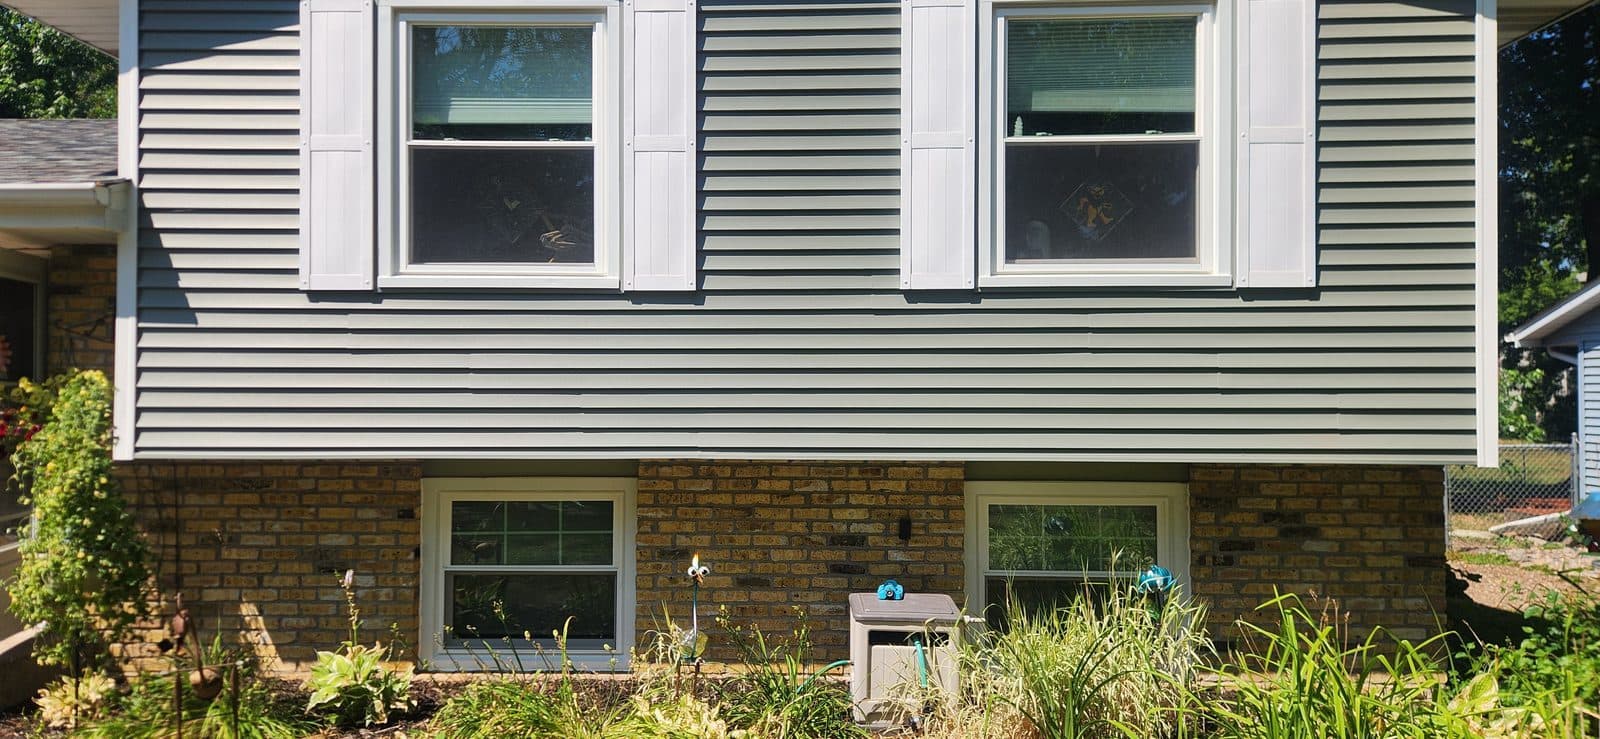
Every claim is tied to a date of loss: the day the covered event happened. On a hail claim that is the storm that did the damage, and it matters. Your policy has a deadline for reporting a loss, your deductible may differ from one policy year to the next, and a storm that hit before you bought the house, or before the current policy started, may not be covered by it. Twin Cities summers often bring more than one hail day, so the date is not always obvious. The reporting deadline and what counts as your policy period are in your policy; check your policy and ask your agent.
The date comes from three places. Public storm reports: the National Weather Service keeps a record of reported hail by location, date and size, and local news and neighbors' claims fill in the rest. Dated photos: your own phone pictures of the house before and after, a realtor's listing photos, an inspection report. And the damage itself. Fresh hail damage looks fresh. Glass cracks have clean edges and the glass may still be on the sill. Dents in aluminum capping and cladding show bright metal before it dulls. Screens are torn with clean edges. Paint and oxidation on the siding and trim show spatter marks where the hail knocked them off.
We walk the house window by window and door by door, photograph each item with a scale reference, and note which damage looks fresh and which is older: an old crack with dirt in it, a dent that has dulled. That separates the storm you are claiming from the wear that was already there. You file the claim, choose the date with your insurer and deal with any dispute; we document what is on the house and do the repair.
Get a written quote for this job
Three photos and a sentence is enough: a reply within one business day, or ask for a free in-home estimate. Or text the photos to 763-204-2099.
What you supply
- The storm date or dates you think it was, and any photos of hail on the ground
- Your own photos of the house from before and after the storm, with their dates
- When you bought the house and any inspection report or listing photos from the purchase
- What the adjuster said about the date or older damage, in writing if you have it
- The claim number once you file
What JMB supplies
- A window-by-window and door-by-door walk with photos and a scale reference
- Notes on fresh damage versus older damage for each item
- Photos of nearby spatter marks, dented capping, screens and soft metals that show the same storm
- A line-item scope of the storm damage, kept apart from older wear
- Meeting your adjuster to walk the house, when you want us there
- The repair once the scope is approved, or paid directly if you do not file
How it is priced: per window
Quoted in writing from your photos, with a reply within one business day. What moves the number:
- Glass only, sash or full window for each damaged unit
- Screens, capping and storm doors on the same storm
- Older damage that is not part of the claim but you want fixed, listed separately
- Matching discontinued windows
- Siding, brick or stucco around full-frame units
Send close-ups of the damage and any photos you have from before the storm, with their dates. Tell us which storm you think it was.
How long it takes
The documentation walk takes an hour or two for a typical house. Windows are made to order once the scope is approved; installing usually runs one to three days for a typical house.
How your project works
- 1
Send photos, get a written quote
Send three photos of the space and a sentence about what you want. You get a clear, itemized reply within one business day. Prefer a look in person? A free in-home estimate is always an option.
- 2
Pick materials, or bring your own
We help you choose profiles and materials that fit the house and the budget, or match your existing millwork exactly — or you buy the door or trim yourself and we install it. Everything is confirmed before the crew is scheduled.
- 3
Clean, precise installation
The crew shows up on time, protects floors and furniture, and installs with tight joints and consistent reveals. Photos of the finished work go in your job folder.
- 4
Walkthrough and invoice
We walk the finished work with you. If anything is not right, we fix it before we call the job done. Then one invoice, paid by check or direct deposit — no card fees, no payment links.
Situations and options
One storm, clear date
Hail hit, you saw it, the damage is fresh. The storm report and your photos match, and the scope lists the damage under that date.
Two storms in one season
Hail came twice and the damage was found later. We note which items look fresh and which have aged, and you and your agent decide which date or dates to report.
Adjuster says the damage is old
The adjuster believes the dents or cracks predate the policy or the storm. We photograph the signs of fresh damage and show older wear separately, so the disagreement is about specific items, not the whole house.
Date of Loss for Hail Claim on Windows — Pinning the Storm: questions, answered
What is the date of loss on a hail claim?
It is the date the storm that caused the damage hit your property. The claim is tied to that date, and it decides which policy period applies and whether the loss was reported in time. If you are not sure of the date, ask your agent how to report it and gather storm reports and dated photos.
How do I find out what day hail hit my house?
Start with public storm reports, which list hail by date, location and size; the National Weather Service keeps a record of them. Check your own phone photos, local news and neighbors who filed claims. Then compare with the damage itself: fresh dents and breaks point to the most recent storm.
The adjuster says my window damage is from an old storm. What now?
Ask for the reason in writing. Then document the signs of fresh damage: clean glass breaks, bright metal in dents on capping and cladding, cleanly torn screens and spatter marks on the siding. Show older wear separately so the disagreement is about specific items. You deal with your insurer; we provide the photos and line items.
How can you tell new hail damage from old on windows?
New damage looks clean: fresh glass cracks with no dirt in them, bright metal in dents on aluminum, screens torn with sharp edges, and spatter marks where paint or oxidation was knocked off. Old damage has dulled, collected dirt or rusted. We note which is which, window by window.
Is there a deadline to file a hail claim after the storm?
Policies set their own reporting requirements, often worded as prompt notice, and some set a time limit. Check your policy and ask your agent. Reporting soon after you find the damage, with the date you believe the storm hit, keeps the question simple.
Can hail damage from before I bought the house be claimed?
Damage from a storm before you owned the house, or before your policy started, is a question for your agent. Usually it is the policy in force on the date of loss that applies. Dated listing photos and the purchase inspection report help show what the house looked like when you bought it.
Recent JMB work, from our job log
59 installs recorded across 30 Twin Cities communities since Dec 2025. Window and door installs for homeowners and the builders we work with. Counts come straight from our job log; no customer names.
Related jobs we do
Window Claim Denied or Underpaid — Re-Inspection, Supplement, Repair
The estimate came back with two windows on it and you have six with cracked sashes. Or it came back as a denial. Here is what the next letter to your insurer should have in it.
Read moreAdjuster Says Hail Damage to Windows Is Cosmetic — What to Photograph
The adjuster walked around, saw dents and chips, and called it cosmetic. Before you accept that, check each window for damage that affects how it works.
Read moreWindow Claim Adjuster Inspection — What They Check and What to Show
The adjuster is coming Thursday morning and you have twenty minutes of their time. What they will look at, what gets missed when nobody points, and what to have on the kitchen table.
Read moreHail Damage Window Replacement — Cracked Glass, Sashes and Frames
Hail left star cracks in the glass, dents in the vinyl sill and a sash that will not close tight. Here is how each one gets fixed, and what goes on the list for your adjuster.
Read moreContractor Estimate for Window Insurance Claim, Line by Line
The adjuster is coming Thursday and you want something on paper that lists every window and door the storm hit. This is what that estimate should look like and what goes in it.
Read moreActual Cash Value vs Replacement Cost — Why the First Check Is Less
The adjuster's estimate says one number, the check that came says a smaller one, and the letter mentions depreciation. Nothing is wrong. Here is what the numbers are and what has to happen for the rest to arrive.
Read morePage reviewed October 9, 2026 · JMB Builders LLC, MN license BC809005 · All insurance repairs pages
Where we work
Insurance & Storm Damage Repairs near you
Based in Zimmerman, scheduling across the Twin Cities metro. Closest first: